Earnest Money Release in Real Estate: Who Signs, When It Happens, and What TCs Should Know
A clear, contract-first guide to signatures, release timing, disputed deposits, and the administrative steps that keep a cancellation from stalling.
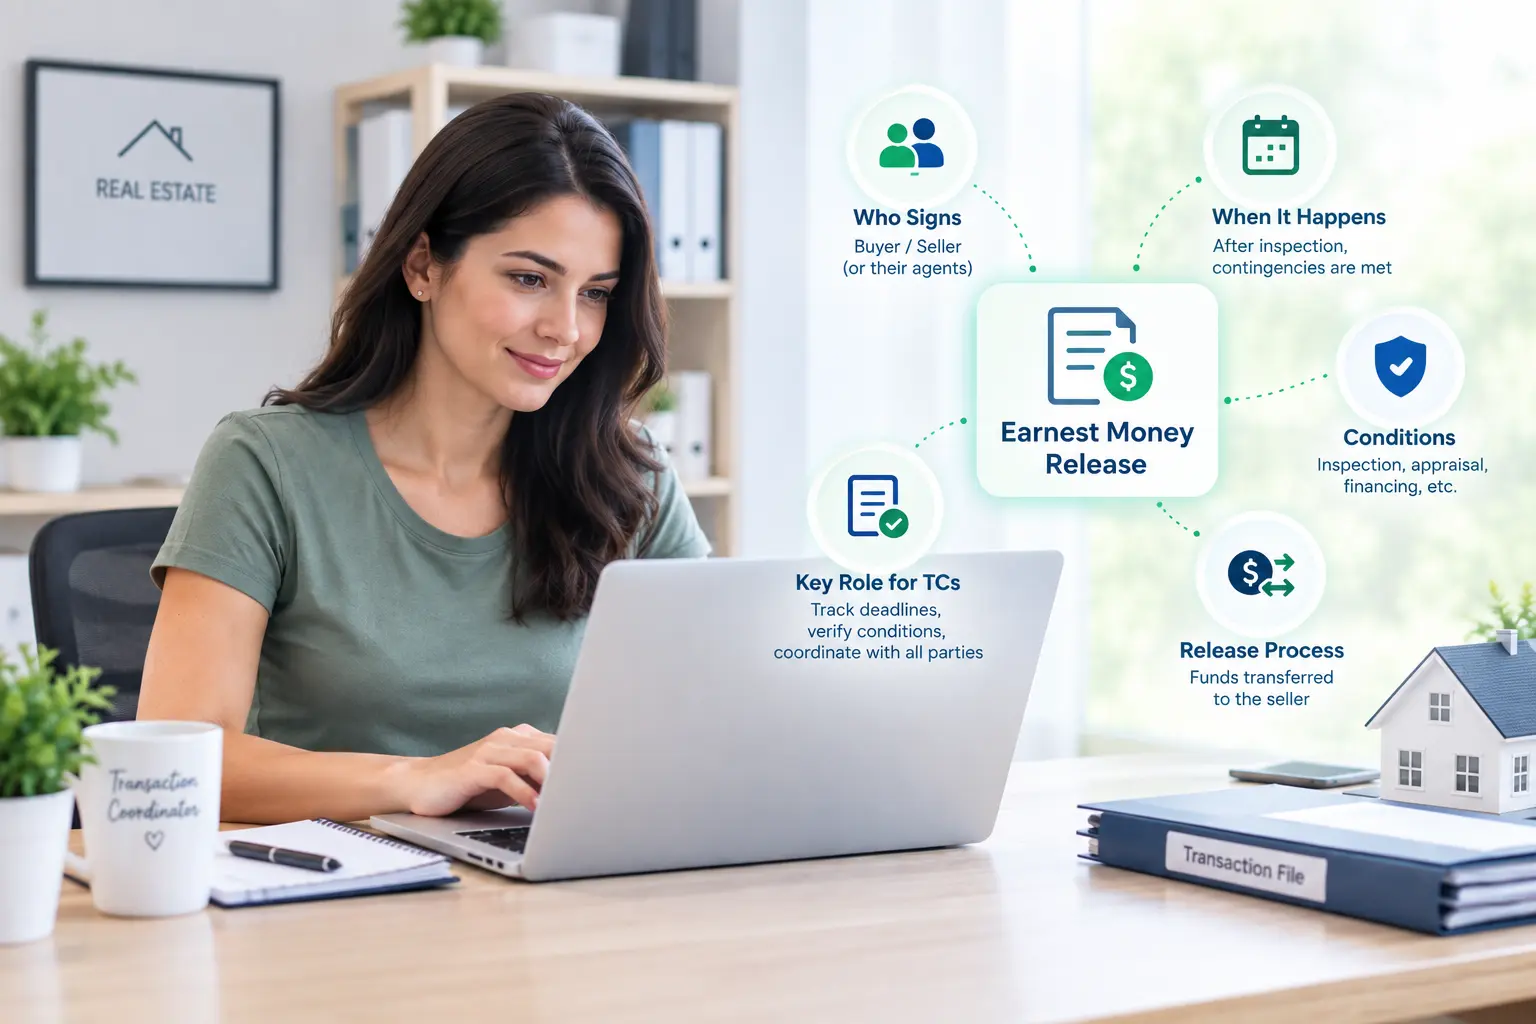
An earnest money release is the written instruction that tells the escrow holder where to send a buyer’s deposit after a contract ends before closing.
In most real estate transactions, all named buyers and sellers sign the approved release. Some forms also require broker signatures. The escrow holder then verifies the document, confirms funds have cleared, and disbursed according to the signed instructions. The purchase agreement, state law, and the holder’s policy-not a national rule- control the details.
Who Signs an Earnest Money Release?
Start with the names on the purchase agreement and the signature lines on the approved release form. The safest operational rule is simple: collect every signature the form requires before sending the package to the escrow holder.
| Party | Typical role | TC verification |
|---|---|---|
|
All buyers |
Approve the cancellation and distribution |
Match every buyer to the contract |
|
All sellers |
Approve the cancellation and distribution |
Check all owners’ signature lines |
|
Broker(s) |
Sign only where the form or brokerage requires |
Do not assume broker signatures are optional |
|
Escrow holder |
Receives instructions and disburses funds |
Confirm receipt and processing requirements |
Why the variation matters: Colorado’s commission-approved form has buyer and seller signature lines and warns that it can affect legal claims. Oklahoma’s 2026 form includes buyer, seller, and broker approvals. Always use the current form for the transaction’s jurisdiction.
When Is Earnest Money Released?
Release usually follows one of four outcomes. Whether the buyer receives a refund depends on the contract language, the timing and delivery of any notice, and the parties’ agreement, not simply on the fact that the deal ended.
Protected Cancellation
The buyer timely uses an inspection, financing, appraisal, title, or other contractual contingency.
Mutual Cancellation
The buyer and seller agree to end the contract and specify how the deposit will be divided.
Alleged Default
One party claims breach. Entitlement may be disputed and funds generally remain held.
Successful Closing
The deposit is ordinarily credited to the buyer on the closing statement, not returned by a release.
The Earnest Money Release Timeline, Step by Step
01
Document the Trigger
Save the termination, cancellation, contingency notice, or mutual agreement with its delivery timestamp.
02
Confirm the Holder
Verify whether the deposit is with a title company, closing attorney, or brokerage trust account, and confirm it cleared.
03
Use the Approved Form
Pull the current state, association, contract, or escrow-holder form. Never improvise release language.
04
Collect Every Required Signature
Check names, property address, contract date, deposit amount, payee, and distribution totals before routing.
05
Deliver and Confirm Receipt
Send the complete release to the escrow holder through the approved channel and record confirmation.
06
Track, Not Promise, the Payout
Ask for the holder’s expected processing window. Follow up until disbursement is confirmed and file the evidence.
How long does the release take? There is no universal deadline. A clean, fully signed release may still require several business days for review, cleared-fund verification, and payment processing. Ask the actual holder for its timeline and avoid promising a date to the parties.
What If the Buyer and Seller Disagree?
If the parties make competing claims, or one refuses to sign, the escrow holder typically keeps the money in trust. The holder is neutral; it does not decide the winner simply because one side appears to have a stronger argument.
THE TC'S ESCALATION RULE
Stop the administrative workflow when it becomes a legal judgment.
Notify the supervising agent or broker, preserve the record, and direct the parties to the remedies in their contract. Those may include a written demand, mediation, arbitration, court order, or interpleader. Do not declare who deserves the funds.
What the TC Can Do
- Record notices, signatures, delivery timestamps, and responses.
- Keep the supervising agent or broker and escrow holder informed.
- Track contractual response dates and scheduled dispute steps.
- Maintain a complete file of the contract, notices, release drafts, and communications.
What the TC Should Not Do
- Interpret whether a contingency was validly exercised.
- Tell a buyer or seller that a refund or forfeiture is guaranteed.
- Draft custom release language or negotiate a division of funds.
- Pressure a party to sign or advise them to waive potential claims.
Earnest Money Release Checklist for TCs
- Termination or cancellation notice saved
- Delivery date and time documented
- Deposit amount and holder verified
- Current approved release form used
- Party names match the purchase agreement
- Distribution instructions total correctly
- Every required signature and date collected
- Escrow receipt confirmed in writing
- Expected processing window recorded
- Final disbursement evidence filed
Five Common Earnest Money Release Mistakes

1. Using an Outdated or Wrong-State Form
Form language and required signatures vary. Confirm the current approved document before routing.
2. Treating Termination and Release as the Same Event
A termination notice may end the contract, but the escrow holder may still need separate disbursement instructions.
3. Missing One Named Party
A spouse, co-buyer, trustee, or entity signer omitted from the release can stop processing.
4. Assuming the Deposit Is Already Available
A deposited check may not have been cleared. Confirm fund status before setting expectations.
5. Giving a Legal Conclusion
A Transaction coordinator coordinates the record and process; the parties, their licensed representatives, or counsel resolve entitlement.
Keep every deadline visible
Coordinate the details. Keep the whole transaction moving.
Frequently Asked Questions About Earnest Money Release
Often, yes. Many release forms require all buyers and sellers to sign before the escrow holder can disburse funds. However, the contract, state rules, and escrow-holder policy control. A few jurisdictions permit disbursement without both signatures in limited, undisputed circumstances.
There is no universal timeline. After the escrow holder receives a complete, correctly signed release and confirms cleared funds, processing may take several business days. State rules, the contract, weekends, bank clearance, and internal escrow procedures can extend that time.
During the contract's dispute process, the escrow holder will typically maintain the funds in an escrow account. This can be either through a formal demand, mediation, arbitration, court order, or interpleader. A TC should raise the matter instead of making any judgment regarding who is entitled to the funds.
At a successful closing, the deposit is normally shown as a credit to the buyer on the closing statement rather than returned through a separate pre-closing release. Confirm the credit and amount with the closing or escrow team.
A TC may be able to complete and route an approved form under the supervising broker's process, depending on licensing and state rules. A TC should not draft custom legal language, decide entitlement, or advise a party whether to sign.
