California Residential Purchase Agreement: 7 Details Real Estate Agents Shouldn't Overlook
The California Residential Purchase Agreement (C.A.R. Form RPA-CA) sets out the terms of a residential property sale, including the purchase price, deposit, financing, contingencies, and closing arrangements.
For real estate agents and transaction coordinators, reviewing the agreement is only part of the work. There are also deadlines to be kept, paperwork to be gathered, follow-up on pending items, and file of transaction documents to be updated as the sale progresses towards closing.
It’s challenging when multiple parties are involved in various aspects of a transaction, to keep them all on view. An amendment may alter a date, a disclosure may be due further examination, or a financing query may surface ahead of the closing.
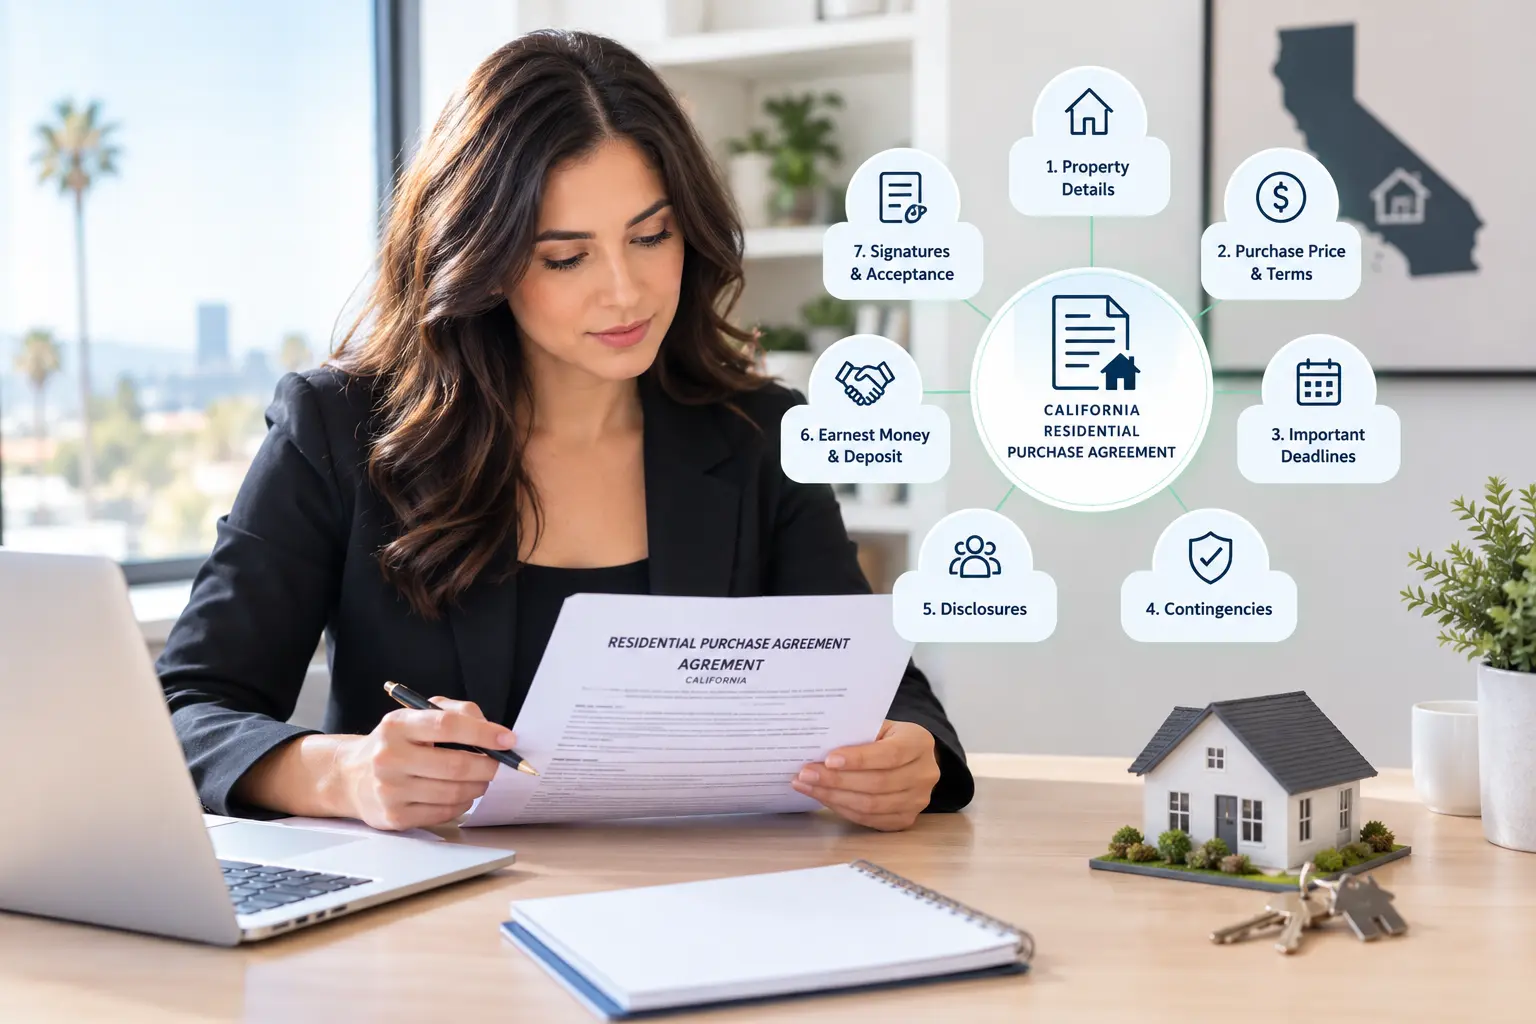
This guide covers 7 areas to review in a California Residential Purchase Agreement and how agents and transaction coordinators can stay organized with the relevant tasks.
Key Takeaways
- Review the purchase price, deposit, financing terms, and closing date against the executed agreement.
- Track each contingency separately and confirm the applicable contractual deadline.
- Understand when a Notice to Buyer to Perform (NBP) may be used and what the agreement requires.
- Review liquidated damages provisions without assuming they apply automatically in every situation.
- Request and review relevant solar ownership, financing, or lease documentation.
- Check seller credits against the agreement, the buyer’s eligible costs, and the lender’s requirements.
- Track required disclosures and any applicable cancellation rights.
What to Review in a California Residential Purchase Agreement

The following seven areas contribute to the agents and transaction coordinators‘ reviewing of significant terms of the contract and organization of the work to be done throughout the transaction. The executed agreement and applicable amendments are the reference points to specific obligations and deadlines.
1. Review the Contract Summary and Key Terms
First, make sure that the transaction information in your workflow is identical with the final signed purchase agreement and addenda.
Pay attention to the things that impact the financial duties of the parties, the real estate being acquired and the closing date.
| Contract detail | What agents should check |
|---|---|
|
Purchase price |
Confirm the agreed price and any signed amendments. |
|
Initial deposit |
Verify the amount, delivery instructions, and contractual deadline. |
|
Financing terms |
Check the selected financing arrangement and related obligations. |
|
Closing date |
Record the agreed close of escrow (COE) date and monitor changes. |
|
Included items |
Review fixtures, appliances, and other items included or excluded from the sale. |
|
Additional terms |
Check relevant addenda, credits, repairs, and other negotiated conditions. |
Why it matters: A discrepancy between the executed agreement and a transaction summary can lead to missed follow-ups or incorrect assumptions about what the parties agreed to.
Practical tip: Create a transaction summary from the final executed documents. When an amendment changes a price, date, or other term, update the record and notify the appropriate parties.
2. Track Each Contingency and Its Deadline
Contingencies describe the contractual rights and duties of both parties to a contract with respect to certain Conditions. They can be loan approvals, appraisal and/or the buyer’s investigation, depending on the agreement.
Real estate contingency periods must be determined from the signed contract and any signed amendments. Don’t assume the number of days is the same in every transaction in California.
Some of the typical contingencies to track:
- Loan contingency: Follow up the financing status of the buyer’s loan and any actions that may be needed if the financing is not obtained.
- Appraisal contingency: Keep track of the appraisal and any problems with the value which may need to be dealt with.
- Follow up under contract: Track track inspections, investigations, document review etc. if there is a follow up under contract.
For instance, let’s say the agreement includes 17 days for the loan, appraisal, and buyer investigation contingencies. The dates should be entered separately for each deadline, although they may be on the same day at first.
The agent or transaction coordinator shall confirm the date of start and provisions regarding time counting as well as any changes in the signed agreement. A calendar reminder is not an extension of a contractual deadline.
Why it matters: Missing a contingency deadline or misunderstanding the required procedure can affect the parties’ contractual options.
Practical tip: Record the deadline, responsible person, required action, and reminder schedule for each contingency. Escalate unresolved issues before the relevant deadline rather than waiting until the final day.
3. Understand the Notice to Buyer to Perform (NBP)
A Notice to Buyer to Perform (also known as an NBP) is a contractual notice used when a buyer has failed to perform a specified action in the purchase agreement.
This should not be considered a no-return notice. The notice may be given at any time as specified in the contract provisions, must cover certain matters and may have certain consequences if the buyer fails to act.
What Agents Should Review
- Determine the unpaid debt. Ensure that it is clear what the buyer has not done and which clause in the contract is relevant.
- Check the agreement’s requirements. Check if the notice is allowed at that stage of the transaction and if it has time limits.
- Verify notice and delivery process. Follow the notice requirements of the contract as applicable in either the applicable form.
- Note the date when the answer is due. Make a calculation on the basis of the agreement and rules.
- Escalate before taking further action. If the buyer doesn’t do so, see the responsible broker or attorney regarding what options are available in the contract.
The date of an NBP may vary based on the nature of the obligation and the form’s edition. Avoid using a generic rule of the calendar or a clause that equates NBP termination as a default.
Why it matters: An improperly timed or delivered notice can create disputes about whether the required procedure was followed.
Practical tip: Keep a record of the outstanding obligation, notice, delivery evidence, response deadline, and follow-up. Before cancellation or other consequential action, confirm the next step with the responsible broker or legal counsel.
4. Review the Liquidated Damages Provision
A liquidated damages provision is an amount of money agreed to in the contract that could be due in the event of a specified breach, as per the contract and applicable law. The provision is often related to the deposit in a residential purchase transaction.
But, a liquidated damages clause does not always entitle a seller to have the deposit returned if a transaction falls through.
California Civil Code Sections 1675, address liquidated damages in qualifying real estate transactions. Section 1675 provides rules relating to the enforceability of certain liquidated damages provisions of residential property transactions such as a statutory presumption for certain amounts and circumstances. Legal treatment will vary depending on the transaction and the requirements.
Items Agents to Review
- Ensure that the specified provision is a part of the signed contract.
- Check the appropriate acknowledgments or initials were signed by the necessary people.
- If there are any deposit and cancellation policies, check them.
- Do not guarantee that a deposit will be forfeited or returned.
- Ask questions about enforceability or entitlement to the broker or an experienced lawyer.
Why it matters: The deposit is a source of conflict if there is a failure in the transaction.
Practical tip: Maintain executed contract and deposit records. In the event of an argument, refrain from making clear legal decisions regarding the ownership of the money.
5. Check Solar Ownership, Financing, and Transfer Requirements
Leasing, financing, outright ownership, or other agreements for a solar panel system can impact a property’s sale. The status of the system may impact on documents required, buyer’s obligations and the process required prior to closing.
Do not assume that every solar installation can be transferred in the same way.
Solar Details to Investigate
| Solar arrangement | What to review |
|---|---|
|
Owned system |
Available ownership, warranty, installation, and system documentation. |
|
Solar lease |
Lease terms, payment obligations, transfer requirements, and any required approval. |
|
Solar loan |
Outstanding financing, lien information, payoff requirements, and transfer terms. |
|
Power purchase agreement (PPA) |
Agreement terms, payment obligations, and requirements for transfer or assumption. |
Ask the seller for the relevant agreements and supporting documents early enough to allow time for review. Confirm whether the buyer, lender, escrow company, or solar provider needs to take additional steps.
A transfer requirement in a solar agreement is not necessarily the same as a deadline in the purchase agreement. Record any applicable contractual deadlines separately from internal follow-up targets.
Why it matters: Unresolved solar obligations can complicate negotiations, financing, or closing preparations.
Practical tip: Create a solar-document checklist as soon as the system is identified. Assign responsibility for obtaining the documents and track outstanding approvals or payoff information.
6. Review Seller Credits Against Contract and Loan Requirements
Eligible closing costs and prepaid expenses can be covered by seller credits. While the amount negotiated and agreed upon in the purchase contract is not always the amount that a buyer’s lender will be able to apply.
Seller contributions will be treated differently in different loan programs, based on occupancy, loan-to-value ratios, allowable costs and underwriting guidelines.
For example, the maximum financing-concession requirements for qualifying conventional loans are included in the interested party contribution guidelines of the Fannie Mae Selling Guide. For a principal residence or second home, the limits are normally:
| Loan-to-value (LTV/CLTV) ratio | Fannie Mae maximum financing concession |
|---|---|
|
Greater than 90% |
3% |
|
75.01% – 90% |
6% |
|
75% or less |
9% |
|
Investment property, all listed ratios |
2% |
These limits are specific to Fannie Mae’s rules. They should not be applied automatically to FHA, VA, Freddie Mac, or other financing arrangements.
Fannie Mae calculates these limits using the lower of the sales price or appraised value. Financing concessions are also subject to eligible-cost restrictions. Contributions exceeding the applicable limits or eligible costs may need to be treated differently under underwriting rules. The lender should determine the appropriate treatment.
Example: A proposed seller credit
Suppose a property has a sales price of $600,000 and the agreement includes a proposed seller credit of $18,000.
The calculation is:
$600,000 × 3% = $18,000
The arithmetic is given as an example. It doesn’t imply that the entire credit is allowed. The limit is in accordance with the lender’s rules and the lower of the sales price or the lender’s appraised value and the credit is not to exceed eligible costs if limits exist.
Why it matters: If a credit is not allowed to be structured, it will need to be clarified and/or revised prior to closing.
Practical tip: Check with the lender and escrow team about the proposed credit early. Ensure that the contract, amendments and closing documents contain the agreed terms.
7. Track Required Seller Disclosures and Applicable Cancellation Rights
A real estate seller disclosure is helpful to a buyer in ascertaining relevant details about the property. This comprises Transfer Disclosure Statements (TDS), Seller Property Questionnaires (SPQ), Lead Based Paint (LBP) reports, Natural Hazard Disclosure (NHD) and further disclosures pertinent to the property.
There are numerous reasons why the disclosure packages vary. It may be based on the characteristics of the property, the type of transaction or the applicable law. For example, Federal Lead-Based Paint (LBP) disclosures are typically required for covered housing constructed prior to 1978 and may be subject to applicable exemptions.
Key Seller Disclosures to Review:
- Identify which disclosures and reports pertain to the property.
- Track who will prepare and deliver the document.
- Review the document to confirm all required information, signatures and sections have been completed.
- Keep a record of when a document was delivered and how it was delivered.
- Review any new disclosed or amended information.
- In the case where there are questions about the rights of the Buyer or if disclosures are required, contact the broker or attorney.
Understand California's statutory cancellation window
California Civil Code Section 1102.3 states that a party has a right to cancel if an oral or written disclosure is made or a material amendment to a disclosure is made, after a transaction has been consummated.
The statutory period is generally 3 business days from the time of personal delivery, or 5 business days from the time of delivery by mail or electronic delivery, if the delivery satisfies the requirements of the statute. The period doesn’t automatically apply to every disclosure or every transaction document that’s delivered after the fact.
The filing of an SPQ or NHD (or other disclosure document) does not start the statutory period provided for in 1102.3. The question is whether the situation and the delivery of documents was within the provisions of the statute, when the disclosure provisions were adhered to, and what was agreed to in the executed contract.
This is important to know as incomplete or late disclosures may affect the rights of the parties, and need to be reviewed immediately.
Keep a log of all disclosures, including the disclosure document’s name, who made the disclosure, date of disclosure, completion and follow-up (if applicable). Where there is a disclosure, which causes a material concern, give it the attention and action it requires in relation to the professional concerned.
California Purchase Agreement Checklist for Agents and Transaction Coordinators
Agents and transaction coordinators can use this checklist as a reminder, but it cannot replace the signed contract or a timeline according to the agreement’s terms and conditions.
At the start of the transaction
- Save and review fully executed Purchase Agreement and applicable Addenda.
- Verify the closing date, financing terms, deposit and purchase price.
- Review all contingencies and make sure that deadlines for any contingencies are noted in the contract.
- Obtain information regarding disclosures, reports and other documents required for the property.
- Look for solar panels or other arrangements that require further documentation.
- Record agreed seller credits and confirm that the lender will review them.
During the transaction
- Monitor contingency-related tasks and unresolved questions.
- Follow up on deposit delivery and other outstanding obligations.
- Track disclosure delivery and retain evidence of receipt.
- Obtain and review relevant solar or other property-specific agreements.
- Confirm seller-credit treatment with the lender and escrow team.
- Record amendments and update affected dates and tasks.
- Escalate potential missed deadlines or contract disputes promptly.
Before closing
- Review the current contractual dates and outstanding obligations.
- Confirm the status of required documents and approvals.
- Check that amendments are reflected in the transaction record.
- Confirm closing arrangements with the appropriate parties.
- Follow escrow's verified funding instructions and independently verify any wire instructions using a trusted phone number before sending funds.
Remember: The checklist supports organization, but it does not determine legal rights or replace the notice and deadline requirements in the executed agreement.
How Transaction Management Software Helps Keep the Details Organized

A California residential purchase transaction can involve multiple parties, overlapping deadlines, disclosures, amendments, and follow-up tasks. Managing those details through scattered emails and separate spreadsheets can make it harder to see what remains outstanding.
A transaction management platform such as Trackxi can help real estate agents, transaction coordinators, and teams organize transaction information, documents, tasks, and updates in one workflow.
For example, a team can use its transaction workflow to:
- Keep important transaction details and documents organized.
- Assign follow-up tasks to the appropriate team member.
- Track outstanding documents and transaction-related activities.
- Monitor progress toward the agreed closing date.
- Keep relevant updates accessible to the people managing the transaction.
The benefit is a clearer view of the work that remains to be done. The team still needs to verify contractual deadlines, follow the applicable notice procedures, and seek professional guidance when legal questions arise.
Keep Your California Real Estate Transactions Organized
A purchase agreement sets the foundation for the transaction, but successful coordination also depends on what happens after the parties sign. Reviewing key terms, tracking contingencies, organizing disclosures, and following up on outstanding tasks can help the team stay informed throughout the process.
Use a consistent workflow to keep responsibilities visible, address potential issues early, and coordinate the steps leading to closing.
Explore Trackxi to see how transaction management software can help your team organize documents, tasks, and transaction updates.
Frequently Asked Questions About California Residential Purchase Agreement
A California Residential Purchase Agreement is a contract that sets out the terms under which a buyer agrees to purchase residential property from a seller. Depending on the agreement, it may address the purchase price, deposit, financing, contingencies, closing date, disclosures, and other obligations.
Agents should track the deadlines specified in the executed agreement and applicable amendments. These may include deposit delivery, contingency periods, disclosure-related actions, contractual notices, and the closing date. The exact deadlines depend on the agreement and transaction.
The consequences depend on the executed agreement, the contingency involved, the notices delivered, and the actions taken by the parties. A missed deadline does not justify assuming that the contract has automatically ended or that a deposit has automatically been forfeited. The responsible broker or attorney should review the circumstances before consequential action is taken.
No. Seller credits must comply with the purchase agreement, applicable lender rules, and restrictions on eligible costs. The lender should confirm the permitted amount and treatment for the specific financing arrangement.
No. California Civil Code Section 1102.3 provides a specific cancellation period in qualifying circumstances. The period generally depends on the delivery method, and the statute applies to disclosures covered by the relevant article. It should not be assumed to apply to every late-delivered document.
