Title and Escrow in Real Estate: What Happens Between Contract and Closing
A signed purchase agreement starts a series of deadlines, document requests, title reviews, and closing preparations. When a requirement or handoff is missed, the closing timeline can be affected. Understanding how title and escrow work together helps real estate agents and transaction coordinators keep each next step visible.
Title and escrow are connected, but they are not the same thing. Title work examines ownership records and prepares for title insurance. Escrow or settlement coordinates money and documents according to the transaction instructions. Depending on the state, a title company, escrow agent, attorney, or more than one provider may handle those functions. For agents and transaction coordinators, the practical job is to connect each provider’s requests to the contract deadlines and keep the right people informed.
Title vs. Escrow: Two Jobs Working Toward One Closing
Title refers to legal ownership rights in a property. Title professionals search and examine relevant records, identify items that need attention, and prepare a title commitment, the insurer’s offer to issue a policy subject to its terms. Title services can include searching, examination, commitments, insurance, and closing-related work. The CFPB’s overview of title and closing services describes how these services may be arranged differently around the country.
Escrow is a process for handling money or documents under instructions and agreed conditions. In a home purchase, the contract identifies how earnest money is delivered and what happens to it. A third party, such as an agent or title company, may hold that deposit; if the transaction closes, it may be credited toward closing costs or the down payment. If the contract ends, its terms and any required release process govern what happens next. The CFPB’s earnest-money definition explains how the deposit may be handled when a transaction closes or is terminated.
A provider may perform both title and settlement work, but that does not make the work interchangeable. Ask who is conducting the search, who is holding the deposit, who prepares the settlement figures, and who is authorized to disburse funds. Confirm the answers with the parties responsible under the contract and local rules.
A title commitment is a working document. Distinguish the requirements that must be satisfied before policy issuance from the exceptions that may remain outside coverage.
The Title and Escrow Process: 6 Steps From Contract to Closing
There is no universal calendar for every sale. The contract, lender, title condition, property type, and state practice determine the actual schedule. Use the following as an orientation map, then enter the dates and responsibilities from the signed agreement into the transaction plan.
01
Open the File and Calendar the Contract
Send the fully signed agreement and amendments to the parties who need them. Confirm the escrow or settlement contact, where earnest money must go, and the deposit deadline. Calendar inspection, financing, appraisal, title-review, document, and closing dates from the actual contract, not from a generic checklist.
Agent / TC handoff: confirm receipt, responsible party, and proof of delivery for every time-sensitive item.
02
Deliver Earnest Money as Instructed
Follow the contract’s amount, recipient, delivery method, and deadline. Obtain a receipt or written confirmation and save it with the file. Do not assume a deposit is automatically refundable or forfeited: contingencies, notices, deadlines, and release procedures depend on the contract and applicable law.
Never rely on changed wiring details sent by email alone. Verify payment instructions using a known, independently confirmed phone number.
03
Start Title Review and Share the Commitment
The title provider researches the public record and issues a title commitment when ready. Review Schedule A for the proposed insured, property, and coverage details. In Schedule B, separate requirements, which are steps or documents needed before policy issuance, from exceptions, which are matters the policy will not cover unless changed or removed under the commitment’s terms. The ALTA form itself separates these sections; an agent should route legal or coverage questions to the title professional or the client’s attorney.
Track each open requirement, its owner, next action, and status. Do not describe every exception as a defect that will necessarily be cleared.
04
Manage Contingencies and Lender Work in Parallel
As title is being reviewed, buyers may be doing inspections, negotiating repairs, getting loan approval, and satisfying appraisal or insurance requirements. Sellers may be providing payoff, association information, and signatures. Agents and transaction coordinators help coordinate updates, while buyers, lenders, title professionals, and other parties handle their respective decisions and approvals.
If a deadline is in danger, call it before it passes and comply with the notice and amendment process in the contract.
05
Confirm the Figures and Signing Package
The settlement provider gathers charges, credits, payoffs, taxes, and funds due. For a mortgage covered by the applicable disclosure rules, the borrower must receive the Closing Disclosure at least three business days before closing. Review it promptly against the Loan Estimate and contact the lender or closing agent about discrepancies. Ask the closing agent which other documents will be ready to review in advance. The timing rule and exceptions apply to covered mortgage loans, not every cash or property transaction.
Buyer’s agent: coordinate access to the disclosure and closing instructions; do not interpret loan terms as a substitute for the lender.
06
Sign, Fund, Record, and Confirm Possession
At closing, the parties execute the documents needed for the transaction and provide the money via the method authorized by their transaction. Recording funding, disbursing, and possession need not be done in the same order or at the same time in all locations. Follow your title or settlement professional’s state and company instructions; confirm these transactions are completed, deed recorded, keys transferred, and any post-closing is completed before reassuring your clients the sale is final.
Keep clients informed about the closing status, key transfer, and any outstanding post-closing tasks.
Illustrative Contract-to-Closing Timeline
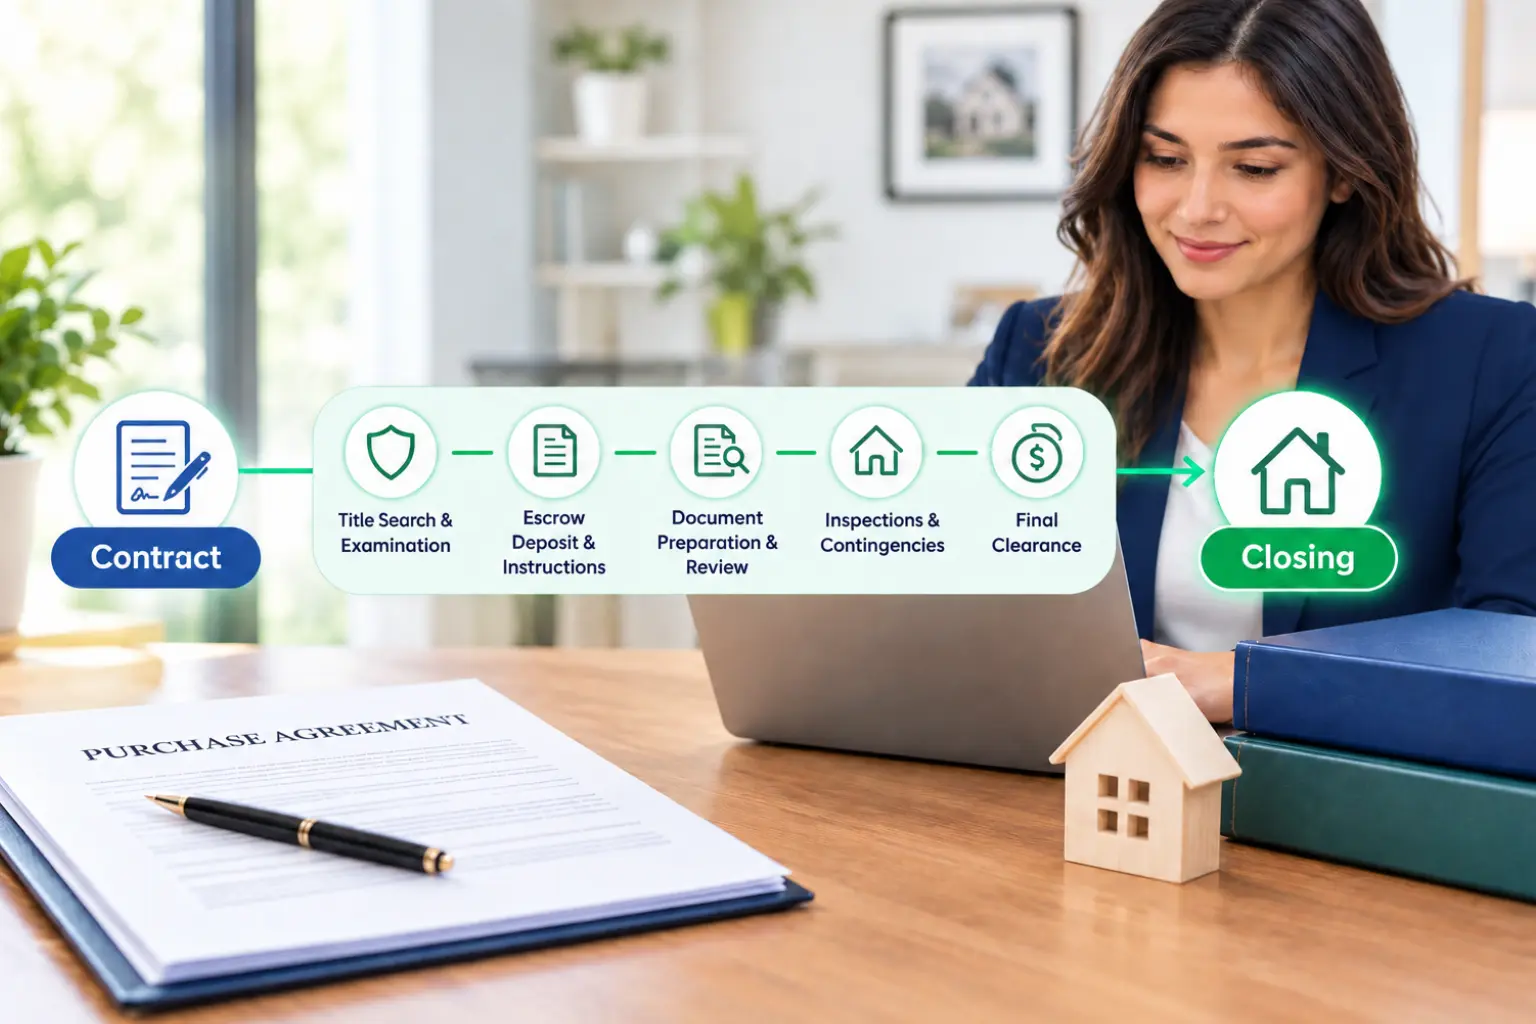
Acceptance & file opening → earnest-money delivery → title search and commitment → inspection, financing, and title items → final disclosure and signing preparation → closing and locally required funding/recording steps. The intervals are set by the agreement and local practice; this sequence is not a deadline template.
Who is Responsible for Each Part of the Process?
People often say “the title company is handling closing,” but a smooth file still depends on clear ownership of each task. Responsibilities below describe common coordination patterns, not a legal allocation of duties for every state or contract.
| Party | Typical role in the file | Coordination checkpoint |
|---|---|---|
|
Buyer / seller |
Meet contract obligations; provide information, signatures, and funds; make decisions about contingencies. |
Confirm receipt of requests and escalate questions to the appropriate professional. |
|
Real estate agent |
Guide the client through contract milestones, coordinate communication, and help keep notices and follow-ups visible. |
Use dates from the signed agreement; do not give legal or title-insurance opinions outside your role. |
|
Transaction coordinator |
Organize the file, route documents, maintain a deadline and task view, and follow up with assigned parties. |
Record who owns the next action, due date, status, and evidence of completion. |
|
Title / escrow / settlement provider |
Perform the services assigned locally, which may include title research, commitment, settlement statements, document coordination, funds, or recording. |
Confirm exact scope, open requirements, funds procedure, signing plan, and completion status. |
|
Lender |
Manage underwriting, loan conditions, loan documents, and applicable mortgage disclosures and funding. |
Ask the lender directly about outstanding conditions, disclosure timing, and wire readiness. |
|
Closing attorney, where used |
May advise, prepare or review documents, conduct the closing, or oversee state-specific steps, depending on jurisdiction and engagement. |
Direct legal interpretation and jurisdictional questions to the attorney. |
Title and Escrow Closing Checklist: Documents and Deadlines
Build the file from the signed contract and the providers’ actual instructions. A practical checklist may include:
- Executed purchase agreement and amendments: price, parties, dates, contingencies, deposit instructions, possession, and any changes.
- Earnest-money receipt: amount, delivery date, holder, and any contract-required follow-up.
- Title commitment and supporting requirements: review items, named insureds, exceptions, and questions sent to the title professional.
- Contingency records: inspection and repair documents, notices, financing status, appraisal-related actions, and written extensions or waivers where applicable.
- Closing figures and lender disclosures: compare amounts and credits, confirm how funds should be delivered, and ask the responsible provider about discrepancies.
- Signing and completion records: signing appointment or remote instructions, funding and recording confirmation where applicable, possession timing, and remaining post-close items.
Why Title and Escrow Closings Get Delayed

Most avoidable last-minute problems result from coordination gaps rather than extra steps in the process. Unresolved title requirements, late payments or payoff/association documents, unsigned or unshared contract amendments, outstanding lender conditions, disclosure errors, and delays in delivering closing funds are examples of such occurrences.
When the closing process slows down, it is essential to locate the outstanding issue, the party responsible for resolving it, and the expected date of the issue’s resolution. It is also vital to update relevant stakeholders about the expected changes to the timeline, address the amendment to the contract and all parties involved to acknowledge the update if necessary, and utilize written correspondence to reflect the situation update. Avoid promising a closing date until the lender and settlement professionals have confirmed the timing.
Transaction management software can help keep the coordination work organized without replacing title services or legal guidance. With Trackxi agents and transaction coordinators can assign tasks, track the progress of their transactions, and receive reminders for upcoming deadlines. This helps keep follow-ups and transaction documents organized while title professionals handle title searches, commitments, and closing services.
Why State-by-State Practices Matter
There is no single nationwide division of responsibility for title companies, escrow agents, and attorneys. The CFPB notes that settlement agents and closing formats differ by state. For example, California regulates independent escrow companies separately, while some “controlled escrows” may be conducted by title companies, brokers, or attorneys under different oversight. In North Carolina, statute governs the order for recording certain documents and disbursing funds. Washington’s escrow rules address written instructions and how an escrow agent performs the assigned services. These examples illustrate variation; they are not instructions for another jurisdiction.
Before setting a workflow, ask the local closing professional which provider handles each function, how earnest money is held, what must happen before funds are released, and who confirms recording and possession. For a legal interpretation, use a qualified attorney in the relevant state.
KEEP THE PROCESS VISIBLE
Keep Every Transaction Handoff on Track
Keep contract dates, follow-ups, and document status organized in one shared transaction workflow. Trackxi helps real estate agents and transaction coordinators manage tasks, track progress, and stay on top of deadlines while title, lending, and legal professionals handle their respective responsibilities.
Frequently Asked Questions About Title and Escrow
Title work examines ownership records and supports the title-insurance process. Escrow or settlement coordinates funds and documents under the contract and local instructions. One provider may handle both, but the functions are distinct.
Not always. A title company may also handle escrow or settlement, while other transactions may involve a separate escrow company, attorney, or another provider. The arrangement depends on state law and local practice.
After the title search, the title company typically issues a commitment outlining the proposed coverage, outstanding requirements, and exceptions. The parties review it and work with the appropriate professionals to address any requirements. The commitment is not the final title insurance policy.
The purchase contract specifies where the deposit must go and the applicable deadlines. Earnest money is typically held by a third party, such as an escrow agent or title company, depending on local practice. If the transaction closes, the deposit is generally credited toward the buyer's closing costs or down payment. If the deal falls through, the contract terms and any required release procedures determine what happens to the funds.
With most mortgage deals, the lender has to give the Closing Disclosure at least three business days before closing. Make sure you know how and when you’ll get it. If it’s missing or the numbers seem off, get in touch with your lender or closing agent right away.
It can, but a change may require written agreement under the contract. If financing, title requirements, documents, or funds are delayed, contact the parties early and consult the responsible professionals about an extension rather than assuming the date changed automatically.
